What if the difference between a contained scam and a life-changing loss is knowing what to do in the first hour—and what not to erase?
How to Recognize Scams, Stop Losses, and Recover with a Better Record
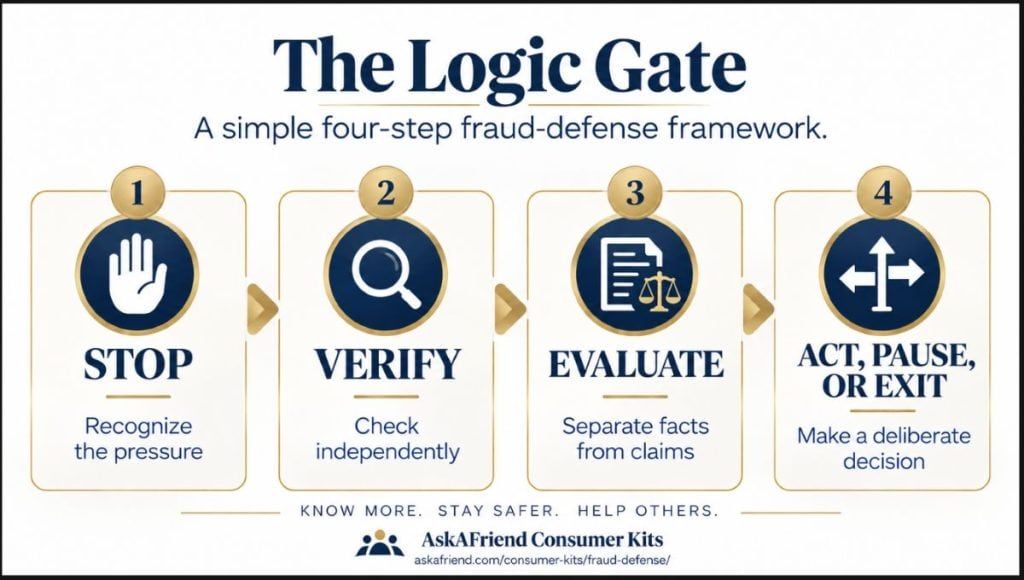
Fraud succeeds by creating urgency, secrecy, confusion, and misplaced trust. Recovery becomes harder when victims keep calling the scammer, delete messages, send another payment, or contact the wrong institution without a clear record. This guide replaces panic with a sequence: stop access, preserve evidence, identify the transaction, notify the organization that can act, use the correct dispute or complaint channel, and track every response. The aim is not to turn the reader into a specialist. It is to make the system visible enough that a decision can be questioned, compared, documented, and carried through. A good consumer guide should reduce dependence on memory and sales language. It should show which facts control, which deadlines matter, which documents prove the point, and when the stakes require licensed advice.
Consumer Fraud is written for consumers and families trying to prevent fraud, respond quickly, or rebuild after a loss. You can read it from beginning to end, but it is also designed to be entered at the point of need. The chapters use plain definitions, realistic situations, practical warnings, action steps, and tools that move information out of your head and onto paper. That structure makes the book useful before a conversation, during a comparison, and after a decision when follow-through matters most.
Short Book Overview
The book connects scam recognition, payment fraud, identity theft, credit reports and freezes, debt collection, online accounts, subscriptions and cramming, insurance disputes, small claims, and recovery and reporting. Those subjects are often handled by different companies, agencies, departments, or professionals, yet the consumer experiences them as one chain of consequences. A choice in one area can change cost, timing, eligibility, risk, leverage, or responsibility somewhere else. The guide keeps those connections in view.
It also treats verification as part of the decision, not an optional final check. A number may change each year. A rule may depend on the state, account, contract, plan, facility, or transaction. A credential may be real while the person offering the service is acting in a different capacity. Rather than hiding that complexity, the book shows readers how to locate the governing document, identify the official source, and write down what was confirmed.
Most importantly, the guide gives the reader a way to move. Understanding without action can still leave a deadline missed or a costly term unchallenged. Each section therefore points toward a next question, a document to gather, a comparison to make, or a professional to involve.
What This Book Helps You Do
- Recognize urgency, impersonation, secrecy, and payment-method red flags.
- Separate unauthorized transactions from consumer-authorized scam payments.
- Lock down accounts and devices without destroying useful evidence.
- Freeze credit and dispute inaccurate reporting with the correct organizations.
- Read debt-validation information and respond within the controlling period.
- Build a chronology of messages, numbers, accounts, amounts, and promises.
- Challenge recurring charges and telecom or utility cramming methodically.
- Prepare an insurer or small-claims record without overstating the law.
- Report identity theft and fraud through verified official channels.
- Document financial, practical, and emotional impact for recovery and sentencing processes.
What You’ll Learn
Scam Recognition and Payment Fraud — Learn how scam recognition, payment fraud shape an actual consumer decision: the terms you will hear, the documents that control, the evidence worth preserving, and the questions that expose a weak assumption. The discussion connects these subjects to cost, timing, risk, and the next decision in the chain.
Identity Theft and Credit Reports And Freezes — Build a working vocabulary for identity theft, credit reports and freezes without stopping at definitions. The guide shows what to compare, where numbers or promises can mislead, how to verify the source, and which written details must survive the conversation if the decision is questioned later.
Debt Collection and Online Accounts — See debt collection, online accounts from the consumer’s side of the table. Each topic is tied to recognizable situations, practical warnings, and an action sequence so the reader can move from a broad concern to a specific record, calculation, question, or professional review.
Subscriptions And Cramming and Insurance Disputes — Understand the tradeoffs inside subscriptions and cramming, insurance disputes and how a choice can change flexibility elsewhere. The goal is to recognize both the visible offer and the less visible consequences—fees, deadlines, exclusions, taxes, eligibility, documentation, or implementation work.
Small Claims and Recovery And Reporting — Use small claims, recovery and reporting as part of one coordinated plan. The guide identifies the decision owner, the proof of completion, the official source to check, and the trigger for revisiting the choice when facts, annual limits, contracts, or family circumstances change.
Where Should I Start?
I just sent money to a scammer — Begin with the chapter and Vault tool closest to this situation. Write down the decision, deadline, and the person or organization that controls the next step. Your first useful objective is to recognize urgency, impersonation, secrecy, and payment-method red flags. Preserve the source documents before relying on anyone’s summary.
My identity or account was stolen — Go first to the relevant comparison or checklist instead of reading the entire book under pressure. Collect the current statement, notice, contract, estimate, or record, and use it to separate unauthorized transactions from consumer-authorized scam payments. Mark what is verified, what is assumed, and what needs professional review.
A debt collector is contacting me — Start by building a short chronology: what happened, what has been promised, what closes next, and what evidence exists. Then use the matching chapter to lock down accounts and devices without destroying useful evidence. This keeps an urgent problem from becoming a vague research project.
A company will not cancel a charge — Use the book to frame the decision before comparing solutions. Name the nonnegotiable need, the realistic alternatives, the total cost, and the failure risk. The immediate task is to freeze credit and dispute inaccurate reporting with the correct organizations. Put the answer in writing so it can guide the next conversation.
My insurer denied a fraud-related claim — Open the tool that matches this issue and fill only the facts you know. Bring the blanks—not guesses—to the responsible professional or official source. That process will help you read debt-validation information and respond within the controlling period. Record the answer, source, and date because the rule or circumstance may change.
I need to report or escalate the loss — Treat this as an implementation problem as well as a learning problem. Identify the document that authorizes the action, the person who must complete it, and the proof that will show it is done. Use the relevant chapter to build a chronology of messages, numbers, accounts, amounts, and promises. Then schedule the follow-up before the conversation ends.
What’s Included
The book includes Fraud Response Workbook, ten Appendix B letters and protocols, credit-freeze and FCRA tools, debt-validation and cancellation letters, small-claims and insurer logs, and identity-theft and victim-impact resources. These are not decorative extras. The scenarios show how a problem develops; the action steps convert the explanation into a sequence; the self-checks test whether the key distinctions are clear; and the worksheets create a durable record for comparison and follow-up.
The primary free companion is the Fraud Response Workbook. The online Vault provides print-ready PDF versions of the appendix materials. Each standalone handout carries the book title, its full source numbering and title, and the direct guide address so a printed page can still be identified later.
Frequently Asked Questions
Why This Book Is Different
The guide is organized around the type of loss and the organization capable of acting, not around a generic command to report everything everywhere. It explains why payment rails, account access, identity misuse, credit reporting, debt collection, insurance, and civil remedies follow different rules. The tools preserve a usable record while keeping readers alert to changing deadlines and jurisdiction-specific law.
Many books stop after explaining terms. This one is built around decision quality. The reader is repeatedly asked to separate a claim from its evidence, a monthly payment from total cost, a title from actual responsibility, and a verbal assurance from an enforceable or reviewable record. That habit makes the guidance useful even when products, thresholds, agencies, and market conditions change.
The tone is deliberately practical. It respects the reader’s ability to understand complexity without burying the next action in jargon. It also respects the limits of general education. When the facts create material legal, tax, medical, safety, or financial consequences, the book identifies the type of professional or official source that should enter the process.
Take the Next Step
You do not need to solve every part of Consumer Fraud today. You need a clearer view of the decision in front of you and a reliable way to take the next step. Read the book, use the companion tools, and bring the written record into the conversations that follow.
Start with the Fraud Response Workbook
Get the free Fraud Response Workbook based on Consumer Fraud. Use it to organize the facts, deadlines, comparisons, and next actions that matter before pressure or uncertainty takes over. You will also receive occasional consumer-education updates and may unsubscribe at any time.