What if the most expensive divorce mistakes happen before anyone realizes a financial decision has already been made?
Elder Care Advocacy – Book Resources
- Divorce & Money – Glossary
- Divorce & Money – Organizations & Resources
- Other Divorce & Money Resources and Free Giveaways
Divorce & Money – News and Articles
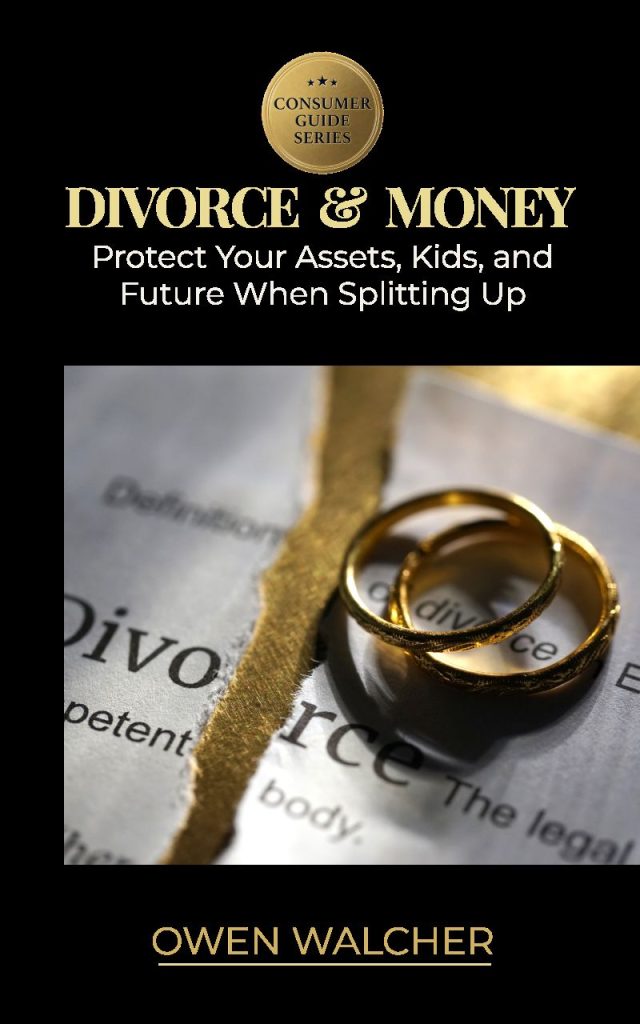
Protect Your Assets, Kids, and Future When Splitting Up
Divorce turns ordinary accounts, debts, benefits, property, taxes, and parenting expenses into a legal and financial system with deadlines and consequences. This guide helps readers preserve the record, understand the moving parts, compare proposals in after-tax terms, and work more effectively with licensed professionals before a temporary choice becomes a binding agreement. The aim is not to turn the reader into a specialist. It is to make the system visible enough that a decision can be questioned, compared, documented, and carried through. A good consumer guide should reduce dependence on memory and sales language. It should show which facts control, which deadlines matter, which documents prove the point, and when the stakes require licensed advice.
Divorce and Money is written for people who need to protect financial stability while a marriage is ending. You can read it from beginning to end, but it is also designed to be entered at the point of need. The chapters use plain definitions, realistic situations, practical warnings, action steps, and tools that move information out of your head and onto paper. That structure makes the book useful before a conversation, during a comparison, and after a decision when follow-through matters most.
Short Book Overview
The book connects first-month protection, professional team, financial disclosure, hidden assets, health coverage, the marital home, retirement and investments, business and executive compensation, debt and taxes, and support, negotiation, and final agreement. Those subjects are often handled by different companies, agencies, departments, or professionals, yet the consumer experiences them as one chain of consequences. A choice in one area can change cost, timing, eligibility, risk, leverage, or responsibility somewhere else. The guide keeps those connections in view.
It also treats verification as part of the decision, not an optional final check. A number may change each year. A rule may depend on the state, account, contract, plan, facility, or transaction. A credential may be real while the person offering the service is acting in a different capacity. Rather than hiding that complexity, the book shows readers how to locate the governing document, identify the official source, and write down what was confirmed.
Most importantly, the guide gives the reader a way to move. Understanding without action can still leave a deadline missed or a costly term unchallenged. Each section therefore points toward a next question, a document to gather, a comparison to make, or a professional to involve.
What This Book Helps You Do
- Protect lawful access, income, credit, records, benefits, and safety early.
- Build a complete asset, debt, income, and document inventory.
- Recognize disclosure gaps and hidden-asset warning signs.
- Track COBRA and Marketplace coverage dates without assuming one clock.
- Test whether keeping or buying out the home is financially sustainable.
- Coordinate QDROs, IRAs, pensions, equity compensation, and business valuation.
- Compare gross asset values with basis, tax, liquidity, and risk.
- Untangle joint debt while recognizing the creditor is not bound by the decree.
- Check child and spousal support inputs and enforcement language.
- Turn a negotiated settlement into specific, implementable final terms.
What You’ll Learn
First-Month Protection and Professional Team — Learn how first-month protection, professional team shape an actual consumer decision: the terms you will hear, the documents that control, the evidence worth preserving, and the questions that expose a weak assumption. The discussion connects these subjects to cost, timing, risk, and the next decision in the chain.
Financial Disclosure and Hidden Assets — Build a working vocabulary for financial disclosure, hidden assets without stopping at definitions. The guide shows what to compare, where numbers or promises can mislead, how to verify the source, and which written details must survive the conversation if the decision is questioned later.
Health Coverage and The Marital Home — See health coverage, the marital home from the consumer’s side of the table. Each topic is tied to recognizable situations, practical warnings, and an action sequence so the reader can move from a broad concern to a specific record, calculation, question, or professional review.
Retirement And Investments and Business And Executive Compensation — Understand the tradeoffs inside retirement and investments, business and executive compensation and how a choice can change flexibility elsewhere. The goal is to recognize both the visible offer and the less visible consequences—fees, deadlines, exclusions, taxes, eligibility, documentation, or implementation work.
Debt And Taxes and Support, Negotiation, And Final Agreement — Use debt and taxes, support, negotiation, and final agreement as part of one coordinated plan. The guide identifies the decision owner, the proof of completion, the official source to check, and the trigger for revisiting the choice when facts, annual limits, contracts, or family circumstances change.
Where Should I Start?
We just separated — Begin with the chapter and Vault tool closest to this situation. Write down the decision, deadline, and the person or organization that controls the next step. Your first useful objective is to protect lawful access, income, credit, records, benefits, and safety early. Preserve the source documents before relying on anyone’s summary.
I am worried about missing money or records — Go first to the relevant comparison or checklist instead of reading the entire book under pressure. Collect the current statement, notice, contract, estimate, or record, and use it to build a complete asset, debt, income, and document inventory. Mark what is verified, what is assumed, and what needs professional review.
I need health coverage — Start by building a short chronology: what happened, what has been promised, what closes next, and what evidence exists. Then use the matching chapter to recognize disclosure gaps and hidden-asset warning signs. This keeps an urgent problem from becoming a vague research project.
We must decide what happens to the house — Use the book to frame the decision before comparing solutions. Name the nonnegotiable need, the realistic alternatives, the total cost, and the failure risk. The immediate task is to track COBRA and Marketplace coverage dates without assuming one clock. Put the answer in writing so it can guide the next conversation.
Retirement or a business is involved — Open the tool that matches this issue and fill only the facts you know. Bring the blanks—not guesses—to the responsible professional or official source. That process will help you test whether keeping or buying out the home is financially sustainable. Record the answer, source, and date because the rule or circumstance may change.
I am reviewing a settlement before signing — Treat this as an implementation problem as well as a learning problem. Identify the document that authorizes the action, the person who must complete it, and the proof that will show it is done. Use the relevant chapter to coordinate QDROs, IRAs, pensions, equity compensation, and business valuation. Then schedule the follow-up before the conversation ends.
What’s Included
The book includes Divorce First Decisions Workbook, sixteen Appendix B tools, asset and debt inventories, coverage and QDRO trackers, settlement and BATNA worksheets, and post-decree audits. These are not decorative extras. The scenarios show how a problem develops; the action steps convert the explanation into a sequence; the self-checks test whether the key distinctions are clear; and the worksheets create a durable record for comparison and follow-up.
The primary free companion is the Divorce First Decisions Workbook. The online Vault also provides editable ODT and print-ready PDF versions of the appendix materials. Each standalone handout carries the book title, its full source numbering and title, and the direct guide address so a printed page can still be identified later.
Frequently Asked Questions
Why This Book Is Different
The book does not treat a settlement as a simple split of account balances. It follows the implementation risk: who owns the account, what document controls, what tax basis travels with the asset, what creditor still has rights, what deadline closes, and what separate order or transfer must occur. It helps the reader see the agreement as a set of future actions, not just percentages on paper.
Many books stop after explaining terms. This one is built around decision quality. The reader is repeatedly asked to separate a claim from its evidence, a monthly payment from total cost, a title from actual responsibility, and a verbal assurance from an enforceable or reviewable record. That habit makes the guidance useful even when products, thresholds, agencies, and market conditions change.
The tone is deliberately practical. It respects the reader’s ability to understand complexity without burying the next action in jargon. It also respects the limits of general education. When the facts create material legal, tax, medical, safety, or financial consequences, the book identifies the type of professional or official source that should enter the process.
Take the Next Step
You do not need to solve every part of Divorce and Money today. You need a clearer view of the decision in front of you and a reliable way to take the next step. Read the book, use the companion tools, and bring the written record into the conversations that follow.
Protect Your Financial Next Step
Download the Divorce First Decisions Workbook
Signup copy: Get the free Divorce First Decisions Workbook based on Divorce and Money. Use it to organize the facts, deadlines, comparisons, and next actions that matter before pressure or uncertainty takes over. You will also receive occasional consumer-education updates and may unsubscribe at any time.